Real Estate Fraud in LA: How Wire Scams, Seller Impersonation, and Deep Fakes Target Homeowners in 2026
I've watched a buyer lose $2 million on a single intercepted closing wire.
Buyers and sellers in Brentwood, Santa Monica, Pacific Palisades, Mar Vista, and Venice are being targeted by people running modern technological operations against an industry that still moves a lot of money over email.
I recently sat down with Kilita Smith, a 20-year escrow veteran and one of the most trusted escrow officers I work with, to talk through what we've both been seeing. What follows is a plain-language breakdown of how the most common, and most expensive, real estate scams work in LA right now, and the steps that actually protect your money.
I'm a real estate agent, not an attorney. Nothing here is legal advice. If you suspect fraud or want to make sure your transaction is structurally protected, talk to a real estate attorney, and pay attention to who is handling your escrow.
How Wire Fraud Actually Works
The mechanics are simpler than people realize. A fraudster, often part of an organized group operating outside the country, gains access to one email account in the transaction. The buyer's, the seller's, the agent's, the lender's, or the escrow officer's. Once inside, they read everything quietly. They learn the signatures, the language, the timing.
Then, just before closing, they send the buyer a fake wire instruction, a near-perfect imitation of the escrow officer's email, complete with branding, signature block, and a "verify" number that goes straight to the fraudster. The buyer wires the money. The account drains within minutes, bounces through multiple banks, often into crypto, and it's gone. By the time anyone realizes, the money is on a different continent.
How to Protect Yourself From Wire Fraud
Three rules. Non-negotiable.
Verbally verify every wire instruction by phone, using a number from the escrow company's website, never from an email. Even if the email looks identical to every other one you've received, call. Read the routing and account numbers out loud, digit by digit.
I will never email you wire instructions. Neither will anyone on my team. If you get an email that looks like it's from me with wire instructions, it isn't me. Call my cell and verify before doing anything.
If a money manager, trustee, or assistant handles your wires, they must verify by phone too. This is where I see the highest losses. Wealthy buyers often have someone else execute the wire, and that person skips the call assuming someone else made it. Don't let them. It's your money. The call has to happen.
Seller Impersonation: The Newer, Scarier Threat
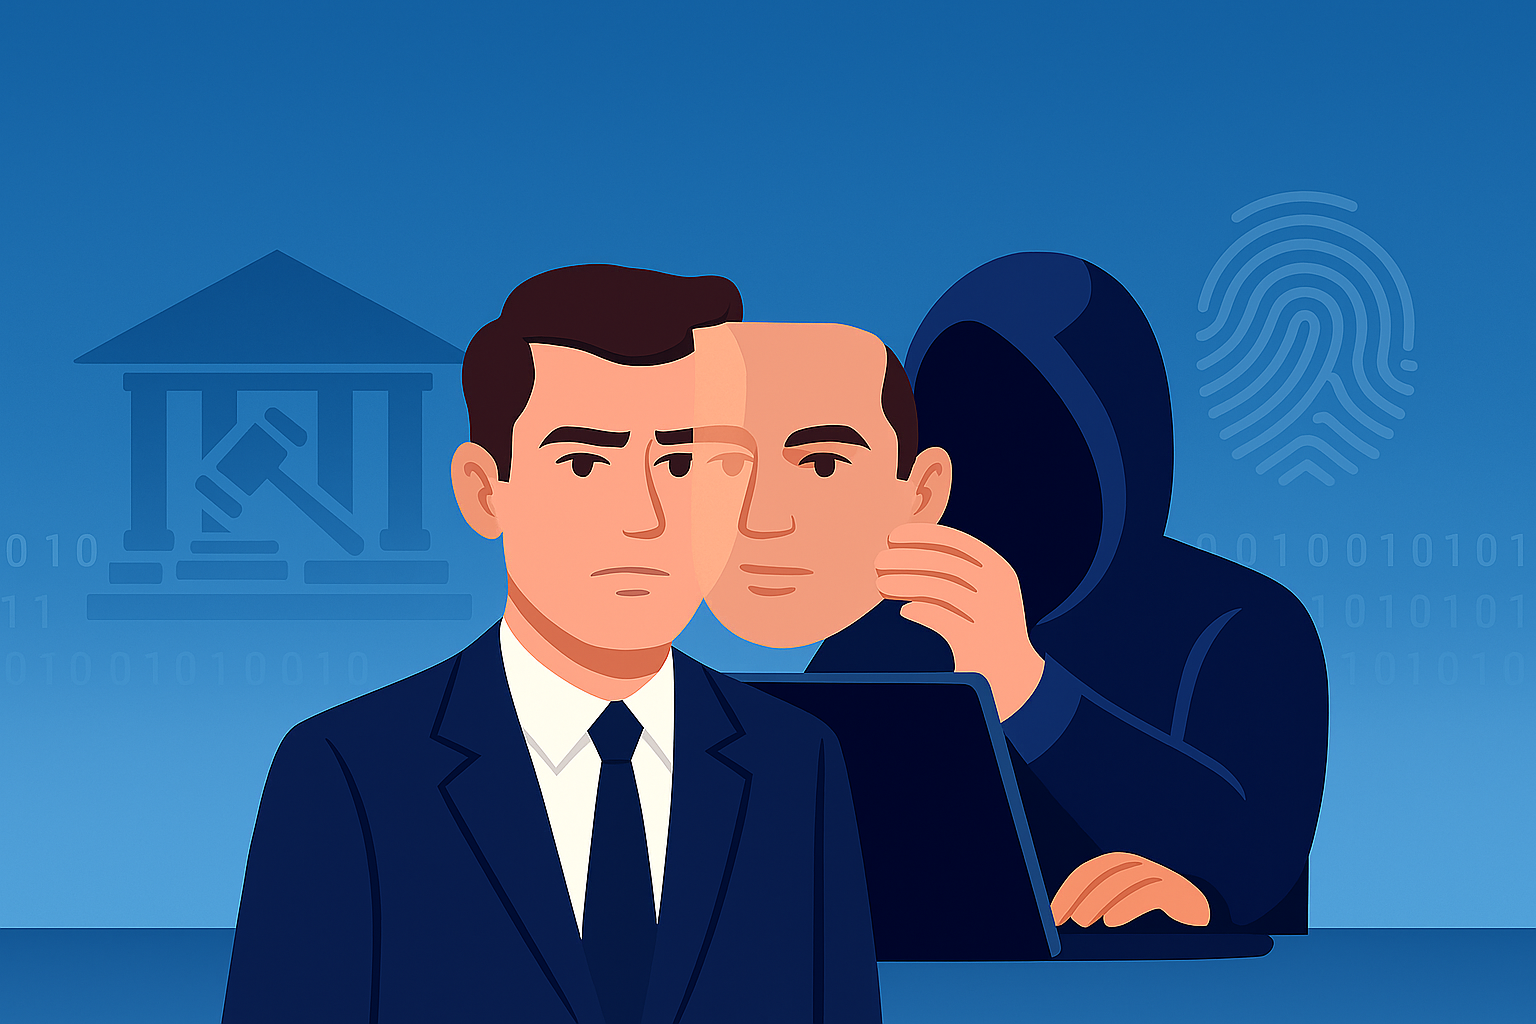
If wire fraud was the dominant threat five years ago, seller impersonation is the dominant threat now.
The setup: a fraudster identifies a property, usually vacant land, often free-and-clear, often with an out-of-state owner, and impersonates the actual owner. They forge IDs, fake LLC operating agreements, fake trust documents. Then they list it and try to sell before the real owner finds out.
Most at risk: vacant land (especially the Palisades and Brentwood burn zones), free-and-clear properties (no lender to slow things down), out-of-state owners (harder to verify in person), and all-cash deals (no underwriter pressure-testing the file). If you own vacant land near a Westside burn area, watch your tax bill, your mail, and any unsolicited offers. If you receive a contract on a property you didn't list, call your real estate attorney and the LA County Recorder immediately.
Deep Fakes Are Already in the Notarization Process
Earlier this year, Kilita had a transaction with an out-of-country seller who couldn't appear at the U.S. embassy. The standard fix is Remote Online Notarization (RON), a video service that lets citizens and green-card holders notarize from anywhere.
The seller appeared on the video call. ID verified. Documents signed. The same day, the RON service flagged the transaction: they believed the seller in the video was a deep fake. The deal was killed. The "seller" disappeared.
This isn't science fiction, it happened on a real Westside transaction, and even a notary verification system caught it only after the fact. The protection is straightforward: if your agent or escrow officer hasn't met the seller in person, ask why. On any high-risk transaction, vacant land, out-of-state owner, all-cash, free-and-clear, in-person identity verification should be the default, not the exception.
What AB851 Changes for Burn-Zone Properties
California AB851 took effect this year specifically to address the surge in fraud targeting burn-area properties. In broad terms, buyers and sellers of properties in or near these zones now sign a notarized attestation that the buyer did not make an unsolicited offer, a documented layer of identity and intent verification that didn't exist before.
For the Pacific Palisades, where most of my listings sit and where most post-fire land transactions are happening, this matters. The law is new and how it's applied will keep evolving, so talk to your agent and attorney about exactly how it applies to your property.
Other Scams Worth Knowing
Check fraud on the buyer deposit. A buyer deposits a check into escrow, then asks a day or two later, before it clears, for the deposit to be wired back as a refund. The check bounces; the wire's already gone.
Hard money lender fraud. Fraudsters file fake loan documents to place a lien on a property they don't own, then "draw" against it. The real owner finds out months later when the lien shows up on title. The common thread in every one: the legitimate parties were moving fast, the verification step got skipped, and by the time anyone slowed down, the money was gone.
What Actually Protects You
Two things matter more than anything else.
An experienced escrow officer who's paid to be paranoid on your behalf. Kilita is the best in this market because she'll say no to a transaction that doesn't seem right. Newer officers don't always have the pattern recognition to catch the subtle signals, such as a delayed seller response, an unusual change to wire instructions, an odd ID.
An agent who's been through this before. I've watched fraud evolve from faked checks to deep-faked video notarizations. Your agent should know the current threat landscape, not the one from five years ago. If they haven't talked to you about wire-fraud verification by closing, that's worth asking about, before, not after.
A Practical Checklist
Before any wire goes out, either direction:
Confirm wire instructions by phone using a number from the escrow company's official website. Never from an email.
Confirm with your agent that the email is legitimate before acting.
If you use a money manager or trustee, require them to verify by phone too.
Treat any change to wire instructions as a red flag, even an extra letter in the email address or a different period in a domain.
If you can't reach your escrow officer or agent on the day of the wire, don't send it. Wait.
For sellers, especially of vacant land or out-of-state property:
Verify your property's tax mailing address is correct and current.
If you get mail from an escrow company about a property you didn't list, call them directly using a verified number.
Consider a property fraud alert through the LA County Registrar-Recorder's office.
Why I Wrote This
Real estate fraud rarely makes the front page, but it costs more on the Westside than people realize, a single closing-day wire-fraud loss here is often $1M to $5M. The people who lose this kind of money aren't unsophisticated. They're sophisticated people who moved fast on the wrong day with the wrong email. The protection isn't expensive. It's a 60-second call to verify a wire. It's an experienced escrow officer who insists on the slower, safer way. It's an agent willing to tell you the awkward truth: yes, even an email that looks exactly like mine could be fraudulent. Verify everything.
Frequently Asked Questions
How does real estate wire fraud work?
A fraudster gets into one email account in the transaction, such as the buyer’s, the agent’s, the lender’s, or the escrow officer’s, and quietly reads the thread. Just before closing, they send the buyer fake wire instructions that look identical to the real escrow emails. Once the buyer wires the money, it moves through several banks or into crypto within minutes and is usually unrecoverable.
How do I verify wire instructions before closing on a home?
Call your escrow officer using a phone number from the escrow company’s official website, never a number from an email. Read the routing and account numbers out loud, digit by digit. If you can’t reach your escrow officer or agent on the day of the wire, don’t send it.
What should I do if my wire instructions change?
Treat any change as a red flag and stop. Even a small difference, like an extra letter in the email address or a different period in the domain, can mean the account has been compromised. Call your escrow officer directly at a verified number before sending anything.
What is seller impersonation fraud?
Seller impersonation is when a fraudster pretends to be a property’s real owner and tries to sell it. They use forged IDs, fake LLC paperwork, or fake trust documents, then list the property and try to close before the actual owner finds out. It’s now one of the most common and expensive scams on LA’s Westside.
Which properties are most at risk for seller impersonation?
Vacant land, free-and-clear properties, homes with out-of-state owners, and all-cash deals carry the highest risk. On the Westside, vacant lots in the Pacific Palisades and Brentwood burn zones are frequent targets because there’s often no lender, no occupant, and no in-person contact to slow the fraud down.
How can I protect my vacant land from being sold by a scammer?
Make sure your property tax mailing address is correct, and watch your tax bill, mail, and any unsolicited offers. If you receive escrow paperwork or a contract on a property you didn’t list, call that escrow company at a verified number, and contact your real estate attorney and the LA County Registrar-Recorder right away. You can also look into the Recorder’s property fraud alert.
What is buyer deposit check fraud?
A “buyer” deposits a check into escrow, then asks for the deposit to be wired back as a refund before the check clears. The check bounces, but the refund wire has already gone out. Escrow should never return funds before a deposit has fully cleared.
What is hard money lender fraud?
A fraudster records fake loan documents to put a lien on a property they don’t own, then draws money against it. The real owner often doesn’t find out until months later, when the lien shows up on title.
Let’s Connect!
If you're buying or selling on LA's Westside in 2026 and have any concern about protecting your transaction, my number is below.
Reach out to us at 310-853-2643 or info@paulsalazargroup.com.